CECL and the WARM method
The Financial Accounting Standards Board (FASB) recommended the Current Expected Credit Loss (CECL) accounting standard for more timely recognition of credit losses to avoid any financial crisis-like situation in the banking industry. The CECL model is now based on expected losses and not on incurred losses. The FASB does not mandate any specific method when measuring credit losses under the CECL standard. One of the methods allowed is the Weighted-Average Remaining Maturity (WARM) method.
Understanding WARM method
It has been observed that the WARM method is one of the more preferred methods of small US financial institutions as they work towards becoming CECL compliant. The WARM methodology lets financial institutions use the same average annual loss rate unlike most other CECL methodologies that calculate a specific lifetime loss rate.
WARM method features
- Calculation of the average annual loss rate
- Based on estimated prepayments and contractual maturities, estimating future outstanding balances
- Multiplication of the estimated outstanding balance by the average annual loss rate during future reporting periods
- Aggregating the estimated losses for each of these periods
WARM method example
There is a loan portfolio with $150,000 outstanding at the end of 2021 in this example. The average annual loss rate for this loan pool has been calculated at 30 basis points. Under CECL, it has been forecasted that the entire loan portfolio will be paid down by 2024.
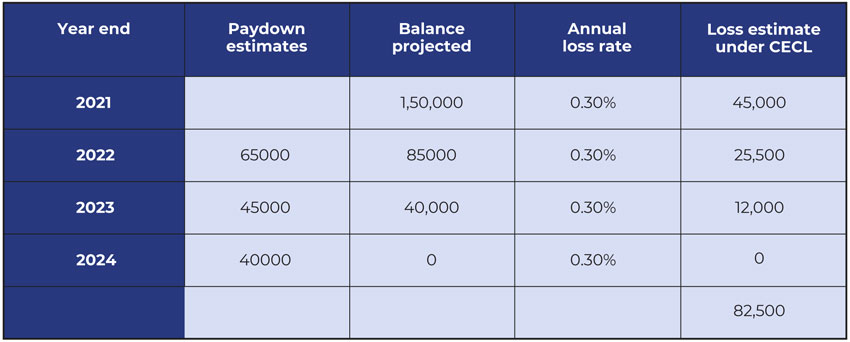
The historical lifetime loss rate = 82,500 / 150,000 = 0.55%
Primary challenges under the WARM method
- Qualitative factors (Q-Factors) need to be considered while using the WARM method. The historical loss rate will be adjusted for current and forecasted economic conditions.
- Forecasting adjustments can be challenging for some entities as they involve key economic indicators such as the consumer confidence index, unemployment data, and housing price index.
- The WARM method does not use loan-level information in the same constructive way as other methods do and does not allow banks to utilize the full potential of their data and analytics capabilities.
Importance of loan portfolio granularity under CECL
Loan pools or segmentations should possess the same risk characteristics and should be as granular as possible. We can have a generic default loss rate number for the pool, or we can split the loan pool into:
- Pass
- Special mention
- Sub-standard
- Doubtful
This split ensures we have a different default for each one of them. The loss rate is different for each as the chance of default is higher for a sub-standard loan than a passing loan. If we do not separate these loans and just allow them to average into the WARM method, we lose the outliers and those outlying loss values.
Trade-offs institutions face while opting for the WARM method
- The WARM method cuts the computation time down as it does the averaging on the way in. But, we do not want to cut the computation time down to the point of losing the granularity of the portfolio.
- The reason the WARM method is used, especially by smaller institutions, is the lower computing power required to execute it.
- If the constraint of computing power is removed, would small financial institutions still use the WARM method? The portfolio has got to be split based on riskiness because otherwise, there is a chance of averaging away the risk that should be captured.
- If banks choose the WARM method, they still have to subdivide their pools into riskiness since the pools will have different driving factors.
- There are methods that are arguably more accurate when it comes to calculating CECL estimates, such as Roll Rate, Discount Cash Flow, and PD/LGD.
If institutions are able to export the computing power cost associated with CECL calculations, then they should also be looking at a provider that offers more optionality in the methods. This way, they can choose a method that is actually right for their portfolio rather than choosing a method that has lower computational requirements.
CECL Express can help…
CECL Express is a turnkey solution that fully satisfies all elements of the new CECL accounting standard. The system provides all non-loan data, including:
- Yield curves and Fed data
- Linked reports on losses from the FFIEC and NCUA
- PD and LGD curves
- Macroeconomic data
Banks and credit unions need to only provide the underlying loan details for the system to provide fully auditable ECL results for multiple calculation methods, including:
- Vintage
- Roll Rate
- Discounted Cashflow
- WARM
- PD/LGD
CECL Express provides more than valid ECL results. The system computes results for all methods and all loan pools, allowing the bank to optimize its CECL configuration and avoid the worst impacts of the new standard.